Bad Debt Counsellor Deregistered and Fined R1 Million
“Hello, I am calling you from the National Credit Regulator and we have some good news for you”
Imagine getting a call that starts like this and then being told that you qualify for massive discounts of 60% on all your debt repayments.
Wow.
Who could resist?
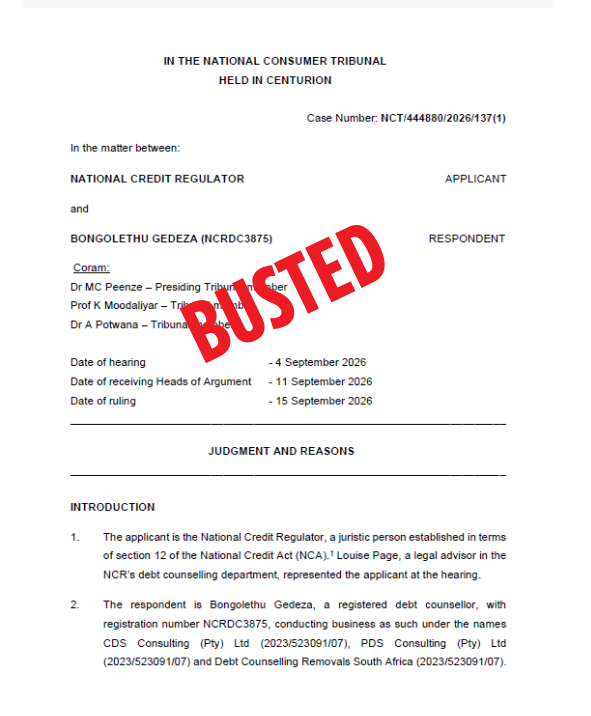
This was one of the fraudulent marketing practices of Bongolethu Gedeza, (NCRDC3875), who had several teams conducting business under such names as CDS Consulting, PDS Consulting and Debt Counselling Removals South Africa before being caught.
Fortunately, the NCR swooped in and shut them down.
Good news For Good Debt Counsellors
Unfortunately, so many consumers were tricked into debt review by such fraudulent lies at CDS Consulting and PDS Consulting.
Others were misled into paying to be removed from debt review by the same company just using a different name (Debt Counselling Removals South Africa). As with so many dodgy people offering debt review removals, the fees they paid upfront were exorbitant.
Fortunately, hundreds of consumers complained. Concerned good Debt Counsellors and Debt Counselling associations repeatedly reported the bad behaviour of CDS to the National Credit Regulator (NCR). Eventually, with hundreds of complaints in place, the NCR moved to investigate and then refer the matter to the National Consumer Tribunal (NCT).
The NCT ruled on the case this year and issued a R1 000 000 fine, deregistered the bad Debt Counsellor and ordered a full audit to see who else has been affected. The idea being to try to set matters straight for the thousands of consumers caught by this trap.
This is great news for an industry plagued by a syndicate of bad actors (sometimes called rogue Debt Counsellors).
What Makes A Bad Debt Counsellor?
While we tend to talk about what makes a good Debt Counsellor, we should also think about what makes a bad Debt Counsellor.
Obviously, not sticking to the requirements of the National Credit Act and regulations is bad. To operate as a Debt Counsellor, this is the bare minimum requirement.
So, to fail at this is unacceptable.
Totally ignoring all suggestions from the NCR (called guidelines) about things like fees and marketing is also bad (even if not legally enforceable). The NCR are trying to guide people to better business practices.
Fraud is also illegal (like pretending to work for the National Credit Regulator when talking to consumers). People go to jail and get massive fines for committing fraud.
Charging people money to get out of debt review in advance is also illegal due to the wording of the National Credit Act.
On top of all that, there is the moral corruption that treats hard working fathers, mothers, pensioners, single parents and vulnerable people in such a despicable way.
It is morally repugnant.
Straight To Jail?
Debt review is designed to help people. It is not designed to be used as a way to trick struggling people out of their hard earned cash.
Hopefully this heralds the first of several cases that will see a network of interlinked operations systematically shut down one by one. The NCR has the complaints and the reports about their behaviour (even though many try to obscure their activity with new business names, new Debt Counsellors and such).
It would be ideal to see such repugnant people lose the ability to operate any business at all, their ill-gotten assets and even better to see them serve jail sentences for their illegal activity. Prosecutions against complicit staff will send strong warnings to others. Strong measures are needed to curb such abuses.
Well done to the NCR and NCT for taking strong steps to stop bad Debt Counsellors who bring the industry into disrepute.
We use cookies (the computer type not the tasty ones) to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.Yummy, Cookies... OKNo