What Does a “Good” Debt Counsellor Mean?
- September 29, 2026
What Does a Good Debt Counsellor Even Mean?
Awards season is a good time to ask what a good debt counsellor looks like.
Here is the uncomfortable part of the answer: it looks like someone delivering a five-year service at a price set eight years ago.
In April 2018, the National Credit Regulator’s debt counselling fee guideline set the restructuring fee at a maximum of R8,000 for a single applicant and R9,000 for consumers married in community of property. The aftercare fee was set at 5% of the monthly distributable amount, capped at R450.
Those numbers were set in 2018. The costs of running a business were not. Since then, Stats SA’s headline CPI figures show a substantial increase in the general price level. The index stood at 74.2 in April 2018 and at 107.7 in July 2026.
From these figures, it can reasonably be argued that the purchasing power of the regulated fees has been materially eroded over the period. Using those CPI figures as an inflation measure, the increase works out at approximately 45%. On that basis, the R450 aftercare cap has the purchasing power of roughly R310 in 2018, while the R8,000 restructuring cap would need to be approximately R11,600 today to have maintained its 2018 purchasing power.
‘the purchasing power of the regulated fees has been materially eroded’
That is everything a practice buys: rent, salaries, software licences, telephone, insurance, the courier who collects signed documents. The cap did not move. The costs did.
The point is not that debt counsellors should simply charge more. Consumers in debt review are, by definition, financially constrained, and the fee structure exists partly to protect them.
The point is what happens to an industry when its price is fixed while its cost base keeps moving.
And that leaves debt counsellors with a choice: deliver less, or find a smarter way to deliver the same service. The fee is fixed. The relationship isn’t.
The Choice
Deliver Less
Or
Find Smarter Ways to Deliver the Same Service
Where the Squeeze Lands
Every party in the debt review chain is working with the same shrinking rand.
Credit providers have often been the most vocal. A restructured instalment negotiated in 2020 is worth less to them every year, while their collection and legal costs rise with inflation. Their complaint is not new, but it has become more significant as the gap widens.
Payment distribution agencies (PDAs) have been under strain for longer than most consumers realize. A PDA earns a small, regulated amount per distribution. It is required to run banking infrastructure, compliance and reconciliation on it. Volumes went up, the per-transaction economics did not, and the agencies have been absorbing the difference for years.
Debt counsellors sit at the end of that chain. A practice earns its restructuring fee once and then services the same client for five years, or sometimes longer, on R450 a month at most. An amount that must cover the servicing of payment queries, creditor correspondence, annual reviews, changes in circumstance, retrenchments, divorces and the occasional court appearance. The debt counsellors and staff doing that work also need annual salary increases, as employees in any other industry do, but the financial limitations are very real.
The point has been made in DCASA discussions this year that the current structure rewards volume. If the fee per client is fixed and the cost per client rises, the only way the arithmetic works is to process more clients with the same human resources or staffing contingent.
The industry has a name for what that produces, and it is not a flattering one. It has comically been quoted in Debt Counselling circles that “a sausage factory does not lose money”. Unfortunately, though a sausage factory manages to not lose money, it also often does not know its clients’ names!
The glaringly obvious reality is that the revenue per client is largely fixed while the cost of servicing that client rises, therefore to mitigate this a practice can either reduce the level of service or increase the number of clients each person has to handle. This is not good for the industry.
What was missing from that discussion, however, is the other way out of the uncomfortable arithmetic. Change what it costs to serve one client well.
The Consumer Is Under Pressure Too
The pressure is not confined to debt counselling practices.
The consumer walking through the door in 2026 is not living in the same economy as the consumer who entered debt review in 2018.
Wesley Sparkman of debt counselling practice, Debt Solutions 4U, says: “Our practice publishes a monthly reading from its own applications, the South African Financial Pressure Index. In August 2026, the median applicant was committing 58.4% of net income to unsecured debt repayments before living costs, across 1,174 applications with complete figures. Fifty-six percent were above the 50% mark. August was also the busiest month we have recorded, with 604 applications.
Those figures are from our own applicant pool, not a national survey, but they illustrate something we are seeing every day: households are under pressure before a debt review plan even begins.
And then something consequential happens.
A debt review plan is built around the consumer’s income and expenses at the time it is assessed. But those numbers do not stand still for five years.
If someone’s salary increases by 3% a year while their essential expenses increase faster, the plan becomes progressively tighter even though nobody has changed a single number in the original arrangement.
Conversely, if their income rises significantly, there may be an opportunity to accelerate repayment.”
The end of a debt review should not look exactly like the beginning.
Not because the original plan was necessarily wrong, but because life changed.
That is why aftercare matters.
Getting Smarter Because We Cannot Simply Get Bigger
If the regulated fee is fixed and inflation is not, a debt counselling practice has two broad choices:
Cut the service
Or
Cut the cost of delivering the service.
The first risks turning debt counselling into a volume ‘sausage factory’ business where clients become just file numbers.
The second is where technology becomes interesting.
At our practice, we have been rebuilding parts of our process around chat, automation and AI—not because technology is fashionable, but because it is not financially feasible to hire another person every time the workload increases.
Most of what a debt counselling practice does in a month is routine.
Confirming that a payment was received. Sending an updated balance. Chasing a payslip. Requesting a missing document. Reminding a client about a payment date. Answering the same questions about the process. Sending a client an update. None of those things necessarily requires a registered debt counsellor to spend their afternoon doing them manually.
Automation can handle much of that work.
Our assessment process, proposal process and document flow can happen within a single conversation on a client’s phone, without printing documents and creating endless email chains. Routine check-ins and document requests can happen automatically. Standard questions can be answered after hours, with anything requiring discernment or judgement escalated to a human during working hours.
And importantly, most of that is automation, not AI.
AI is useful where there is a genuine language or information-processing problem. It can help interpret a client’s message, identify what needs attention, summarize a conversation or provide a first-line response.
But AI must not be confused with debt counselling.
The registered debt counsellor remains responsible for the professional judgement involved in the assessment, recommendation and management of the consumer’s situation.
Technology should take the repetitive work away from the counsellor—not the counsellor away from the consumer.
That distinction matters.
The goal is not fewer people.
It is affording more human time where human judgement actually matters.
Efficiency should not mean less service. It should mean reallocating scarce human capacity.
If a client’s employer has retrenched half of the department, that is a counsellor’s problem. If a creditor is disputing a restructure, that is a counsellor’s problem. If an annual review shows that the plan no longer fits the consumer’s circumstances, that is a counsellor’s problem.
Chasing a payslip for the third time?
A machine can probably help with that.
Technology Has To Work For The Client
There is an important warning here.
Automation built purely to benefit the practice can easily make the client’s experience worse.
A beautifully engineered portal that nobody logs into is not innovation. It is an expensive obstacle.
Debt counselling is a relationship business. Clients need to know what is happening, what they need to do, and who they can speak to when something goes wrong. The technology therefore has to fit the way clients actually communicate.
For many consumers, that means the phone in their hand—not another username, password and portal to remember.
The best technology should feel almost invisible. The client gets the reminder. The client gets the update. The client knows what document is missing. The client can ask a question.
And when the issue becomes complicated, a human takes over.
That is what good automation should look like.
Consumers Cannot Be Passive Either
There is another half to this conversation, and the industry does not talk about it enough.
A debt review is not a product you buy once and then forget about. It is a long-term arrangement that has to survive changes in income, expenses and circumstances. Consumers therefore cannot assume that because a plan worked on day one, it will automatically remain the right plan five years later.
If your salary increase was below inflation, your household may be getting tighter without you realising it. Tell your debt counsellor.
If your expenses have increased significantly, tell your debt counsellor.
If your income has increased, tell your debt counsellor.
If your circumstances have changed, tell your debt counsellor.
And if your financial position has improved, there may be an opportunity to use that improvement to shorten the journey.
At a minimum, consumers should use their annual review to ask three questions:
- What has changed in my income and expenses?
- What has changed in what I owe?
- Does my current plan still work, and is the expected end date still realistic?
The important word is current.
Your debt review is not a photograph. It is a moving picture.
For consumers, it’s also important to be aware that if a practice cannot answer those three questions from its own records within a day, that tells you something about how the practice is run.
So What Does A Good Debt Counsellor Look Like in 2026?
Which brings us back to awards season.
A good debt counsellor in 2026 cannot simply be measured by how many files the practice carries. Nor should technology be measured by how much automation a practice can boast about.
The real question is simpler:
Does the practice still know its clients in year four?
At 2018 prices and 2026 costs, the only sustainable way to answer yes is to become smarter about how the work gets done.
‘the only sustainable way to answer yes is to become smarter about how the work gets done’
Automate the routine. Use technology to communicate better. Use AI where it genuinely adds value. Keep humans responsible for judgement.
And spend the resulting time on the clients who actually need a debt counsellor.
Whether the fee structure should eventually be reviewed or indexed for inflation is a legitimate question for the NCR and the industry to debate. But no practice can build its future around waiting for that to happen.
The practices that will still be delivering excellent service in 2030 will be the ones that have already worked out how to deliver a five-year relationship at a price fixed in 2018.
That means spending the money on technology once, where it makes sense, and spending the people on the clients.
And consumers have a role too.
Stay in the conversation, because a debt review only works as well as the last time somebody looked at it.
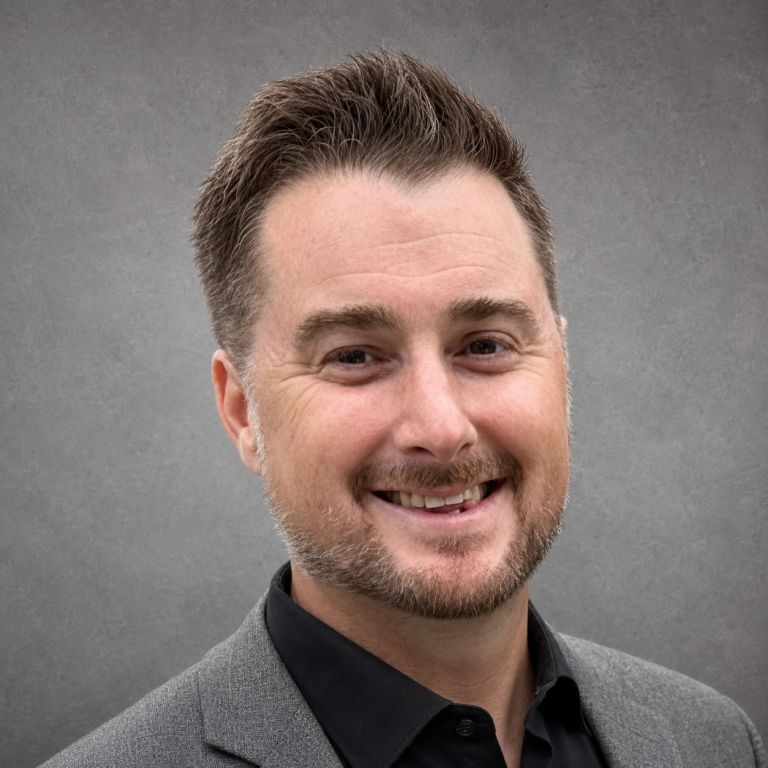
Wesley Sparkman is an NCR-registered debt counsellor (NCRDC1887) and a Director of Debt Solutions 4 U, a DCASA member practice in Centurion. The South African Financial Pressure Index is published monthly by Debt Solutions 4 U.
Thank you to Debt Counsellor Wesley Sparkman for his input in this article.